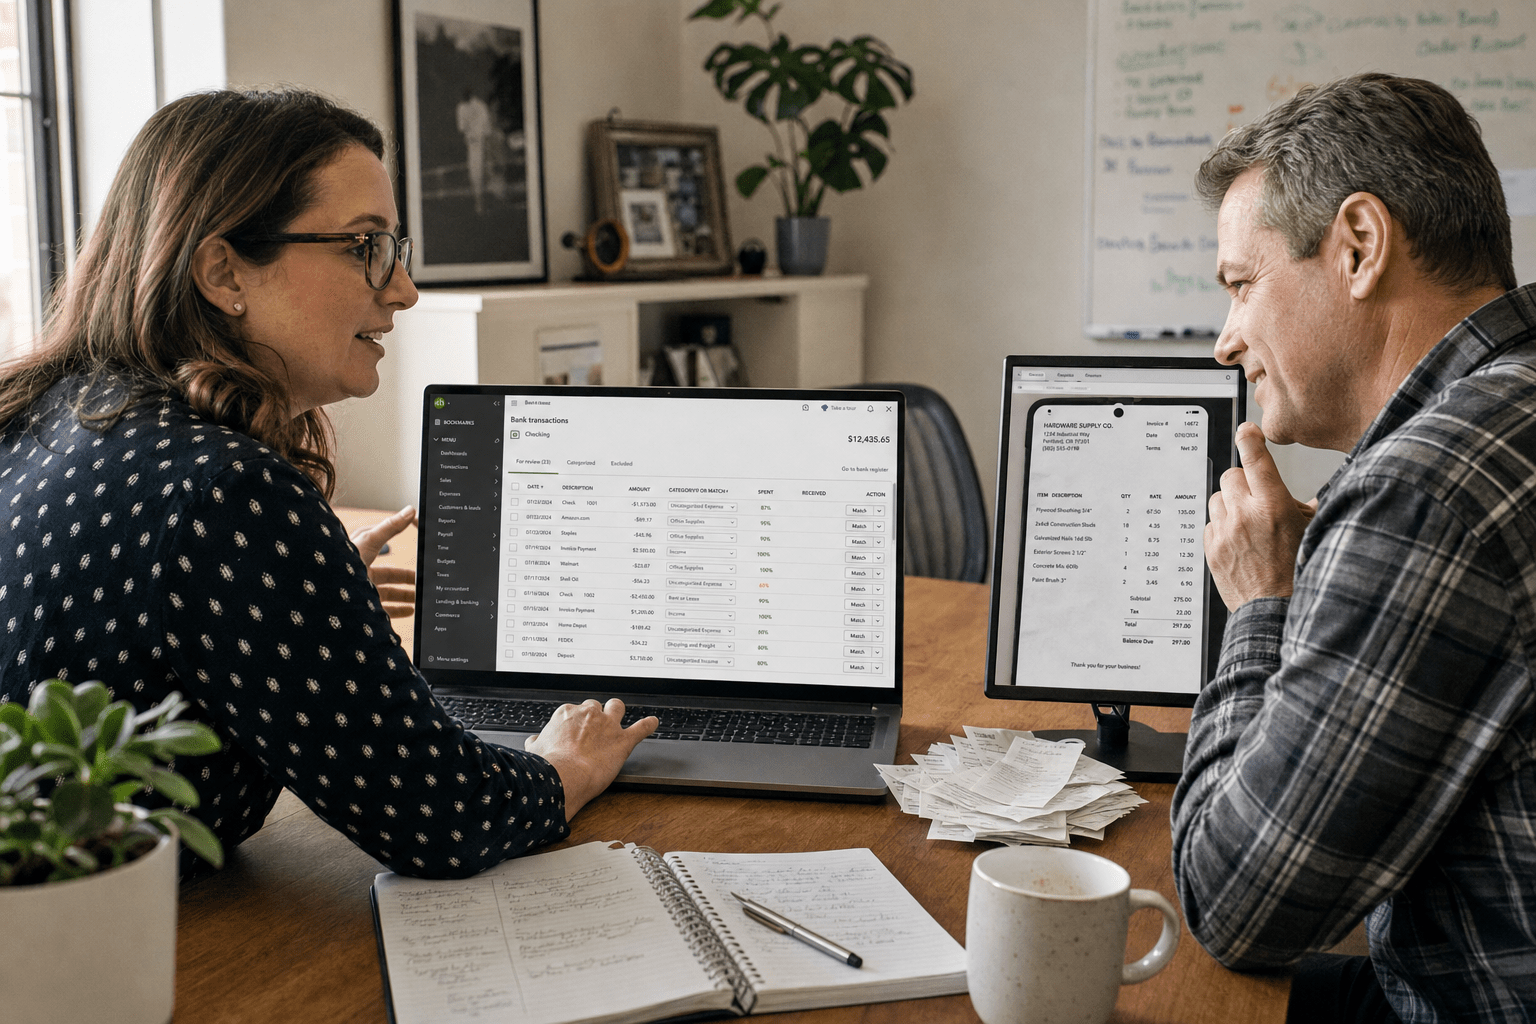
The best AI integration tools for QuickBooks and accounting software are the ones that are honest about what they could not figure out. Every product in this category will tell you it categorises bank feed transactions, reads receipts, and reconciles faster than a person. Most of them do. The part that decides whether a small finance team gets its evenings back is the other side of that claim: what happens to the twelve percent the model was unsure about, how those transactions are presented, and whether the person reviewing them can see why a suggestion was made.
That framing matters because QuickBooks sits in a different position from a full ERP. It is usually run by one or two people who also handle payroll, invoicing, and the chase for unpaid bills. There is no controller with time to audit an automation weekly. So the evaluation question is not which tool has the most connectors. It is which tool leaves a small team with less work at the end of the month than it had at the start.
Overview: 5 Things That Decide a QuickBooks AI Integration
- The review queue is the product. Automated categorisation saves time only if the exceptions arrive grouped, explained, and quick to clear. A flat list of unmatched transactions is the work you already had.
- Accuracy is specific to your vendor list. Published accuracy figures come from a vendor mix that is not yours. Test on your own last three months before signing anything.
- App permissions in QuickBooks Online are coarse. Most connected apps get broad read and write access to your company file. Decide who can connect an app before somebody connects one.
- Bank feed rules and AI overlap. If QuickBooks rules already handle a category correctly, adding a model on top creates two sources of truth and a reconciliation argument later.
- Your exit matters. Ask how a tool’s coding history leaves with you if you cancel, because a year of learned categorisation is real value that can be stranded inside a vendor.
Why Bookkeeping Automation Fails in Small Firms
The failure mode here is not dramatic. Nothing breaks, no numbers go badly wrong, and the tool stays installed. What happens is that the review queue quietly grows, a bookkeeper starts checking every suggestion rather than the flagged ones, and eight months later the subscription renews on a workflow nobody trusts. Our team scopes work like this through our enterprise AI integration practice, and the first conversation is almost always about which decisions a person will keep rather than which ones a tool can take.
Confidence scores are the feature that makes a review queue usable
A model that returns a category and nothing else forces a binary choice: trust it all or check it all. A model that returns a category with a confidence score lets you draw a line. Above the line, transactions post automatically. Below it, they route to a human with the top two or three candidate accounts shown.
There is a fair argument that confidence scores create false comfort, since a model can be confidently wrong and a number on the screen makes that wrongness look considered. Anyone who has watched a receipt coded to the wrong subsidiary with ninety four percent confidence has felt this.
The answer is to treat the threshold as something you tune rather than accept. Start it high, watch how many transactions fall below, and lower it only once you have a month of evidence that the automatic side is clean. Ask a vendor whether the threshold is yours to set or fixed in their product. Fixed thresholds are a strong signal that the tool was built for a demo rather than a close.
New vendors are where the errors concentrate
Categorisation models work from history. A supplier you have paid monthly for two years is easy. A supplier who appears for the first time in September has no history at all, and the model falls back on name similarity, which is how a new software subscription lands in office supplies because another vendor with a similar name lives there.
Some teams accept this and fix it at review. That is reasonable at low volume. It stops being reasonable when a business adds vendors quickly, because first time codings are the ones most likely to become a permanent rule that repeats the error every month afterwards.
The practical control is to route any first time payee to human review regardless of confidence, then let the automation take over from the second transaction. Most products support this. Very few turn it on by default, and almost none mention it during a sales conversation, so it is worth asking for directly.
Duplicate detection deserves its own test
Receipt capture and bank feeds both feed the same ledger, so the same expense can arrive twice by two routes: once as a photographed receipt and once as a card transaction. Good products match them. Weaker ones create a bill and a matching expense, and the duplicate survives until somebody notices the vendor total looks high.
Test this deliberately during a trial. Photograph three receipts that will also appear on the card feed, then check what the tool does when both arrive. If it silently creates two records, you have found the most expensive limitation in the product before you paid for it rather than afterwards.
Where AI Actually Earns Its Place in a QuickBooks Workflow
The category splits into three groups that behave differently: tools that work inside QuickBooks itself, pre accounting layers that clean data before it arrives, and reporting layers that read from the ledger without writing to it. The risk profile drops sharply as you move down that list.
Pre accounting capture, the lowest risk starting point
Receipt and invoice capture tools sit in front of the ledger. They read documents, extract vendor, date, amount, and tax, then push a coded transaction into QuickBooks for approval. Because they write a draft rather than a posted entry, a mistake costs a correction rather than an adjustment.
This is the right first project for most small firms. It removes the genuinely tedious work, the accuracy is measurable within a week, and reversing the decision means turning off a connection rather than unpicking postings. Teams comparing wider tooling across operations will find our overview of managed IT services software useful for seeing where this fits alongside everything else running in the business.
The detail that decides which capture product suits you is how it handles line items. A single line restaurant receipt is easy. A supplier invoice with fourteen lines split across three expense accounts is where products differ, and the ones that force a single coding on a multi line bill will push that work straight back to your bookkeeper.
Categorisation inside QuickBooks, where the gains and the risks both live
QuickBooks Online now ships its own transaction categorisation, and it learns from corrections. Third party tools offer the same thing with more control over thresholds and exception routing. Choosing between them is mostly a question of volume and how much tuning you want.
The argument for staying native is real. One vendor, one permission boundary, no extra subscription, and no question about where your transaction data goes. For a business processing a few hundred transactions a month that is often the correct answer, and the honest recommendation is to exhaust the built in tools and rules before adding anything.
The argument for a specialist tool strengthens with volume, multiple entities, or a bookkeeping firm handling many client files at once. At that scale the ability to set thresholds per client, see accuracy trends, and route exceptions to a named reviewer stops being a nicety. If your business is weighing whether QuickBooks is still the right ledger at all, our comparison of NetSuite and QuickBooks covers where the ceiling usually appears, and our piece on which businesses should switch to NetSuite works through the signals that a move is due.
Reporting and forecasting layers, read only and underrated
Tools that read from QuickBooks and produce cash forecasts, management reports, or commentary carry almost no operational risk, because they never write. They are also the ones most often adopted and then abandoned, for a reason worth naming: a forecast that cannot be interrogated does not get used.
A finance lead signing off a cash plan owns that number. If the tool shows a figure without the receivables and payment assumptions behind it, the sensible response is to rebuild it in a spreadsheet, and the subscription dies at renewal. Ask to see the drivers during evaluation rather than the headline accuracy claim.
There is a wider integration question here too, since reporting across a business usually means pulling data from a CRM and an ecommerce platform as well as the ledger. Our guidance on integrating accounting systems with CRM and ecommerce applies equally when QuickBooks is the ledger at the centre of it.
Permissions, and the app nobody remembers connecting
Connected apps in QuickBooks Online authorise against the whole company file. There is no meaningful way to grant an app access to one account or one class of transaction. That makes the decision about who may connect an app more important than any feature comparison.
Set the rule before you need it. One named person approves connections, the list of connected apps is reviewed quarterly, and anything nobody can explain gets disconnected. Firms in accounting and professional services carry client financial data, which raises the stakes on an app connected during a trial and forgotten. For a broader view of choosing business tooling with this kind of discipline, our guide to IT solutions and tools is a reasonable starting point.
Frequently Asked Questions
Is the AI built into QuickBooks Online good enough on its own?
For most small businesses processing a few hundred transactions monthly, yes, particularly once bank rules are set up properly. Specialist tools earn their cost at higher volume, across multiple entities, or in bookkeeping firms managing many client files where per client thresholds and exception routing matter.
How accurate is AI transaction categorisation in practice?
Accuracy depends almost entirely on how consistent your past coding has been, so vendor benchmarks tell you little. Run a trial against your own last three months and measure how many transactions posted correctly without a human touching them. That figure is the only one worth quoting.
Can these tools post directly to the ledger without approval?
Many can, and most should not at first. Start with the tool preparing transactions for review, establish an accuracy record over a full month, then widen automatic posting to the high volume low risk categories where the evidence supports it.
What happens to my categorisation history if I cancel the tool?
Ask before you sign. Coding learned over a year is genuine value, and products differ in whether that history exports in a usable form or stays inside the vendor. The transactions themselves remain in QuickBooks either way, but the learned model usually does not.
How do I control which apps connect to QuickBooks Online?
Restrict who holds the admin role, since app connections are approved at that level and grant broad access to the company file. Review the connected apps list quarterly and disconnect anything nobody can account for, particularly tools added during a trial that was never concluded.
The Team Behind This Guidance
Our team builds integrations into accounting platforms for businesses that then have to live with them through a close, an audit, and a staff change. That is why we start with permissions and the review queue rather than the connector list. A tool that automates ninety percent of coding and hands back the rest as an unexplained pile has moved the work rather than removed it. Matt Rosenthal, our chief executive, keeps the practice focused on operational resilience for growing firms, which in bookkeeping means automation a business can still run when the person who set it up is on leave.
Start With One Month of Your Own Data
Before shortlisting products, export three months of your own transactions and count how many were coded without a correction. That number is your baseline, and it is usually better than teams expect, which changes what a tool has to beat. Then pick the single most tedious task in your month, capture is the common answer, and trial one product against it alone.
If you want help scoping that against your own QuickBooks setup and the apps already connected to it, book a free strategy call. Our team will review what is connected today, where the review queue is costing you, and which single integration is worth doing first.