The best AI tools for invoice processing automation in 2026 are judged on the invoices that go wrong. Every vendor leads with touchless rate, the share of invoices that flow from receipt to payment with no human involvement, and that number describes the easy half of your inbox. A clean invoice from a known supplier matching an open purchase order was never what kept your accounts payable clerk late.
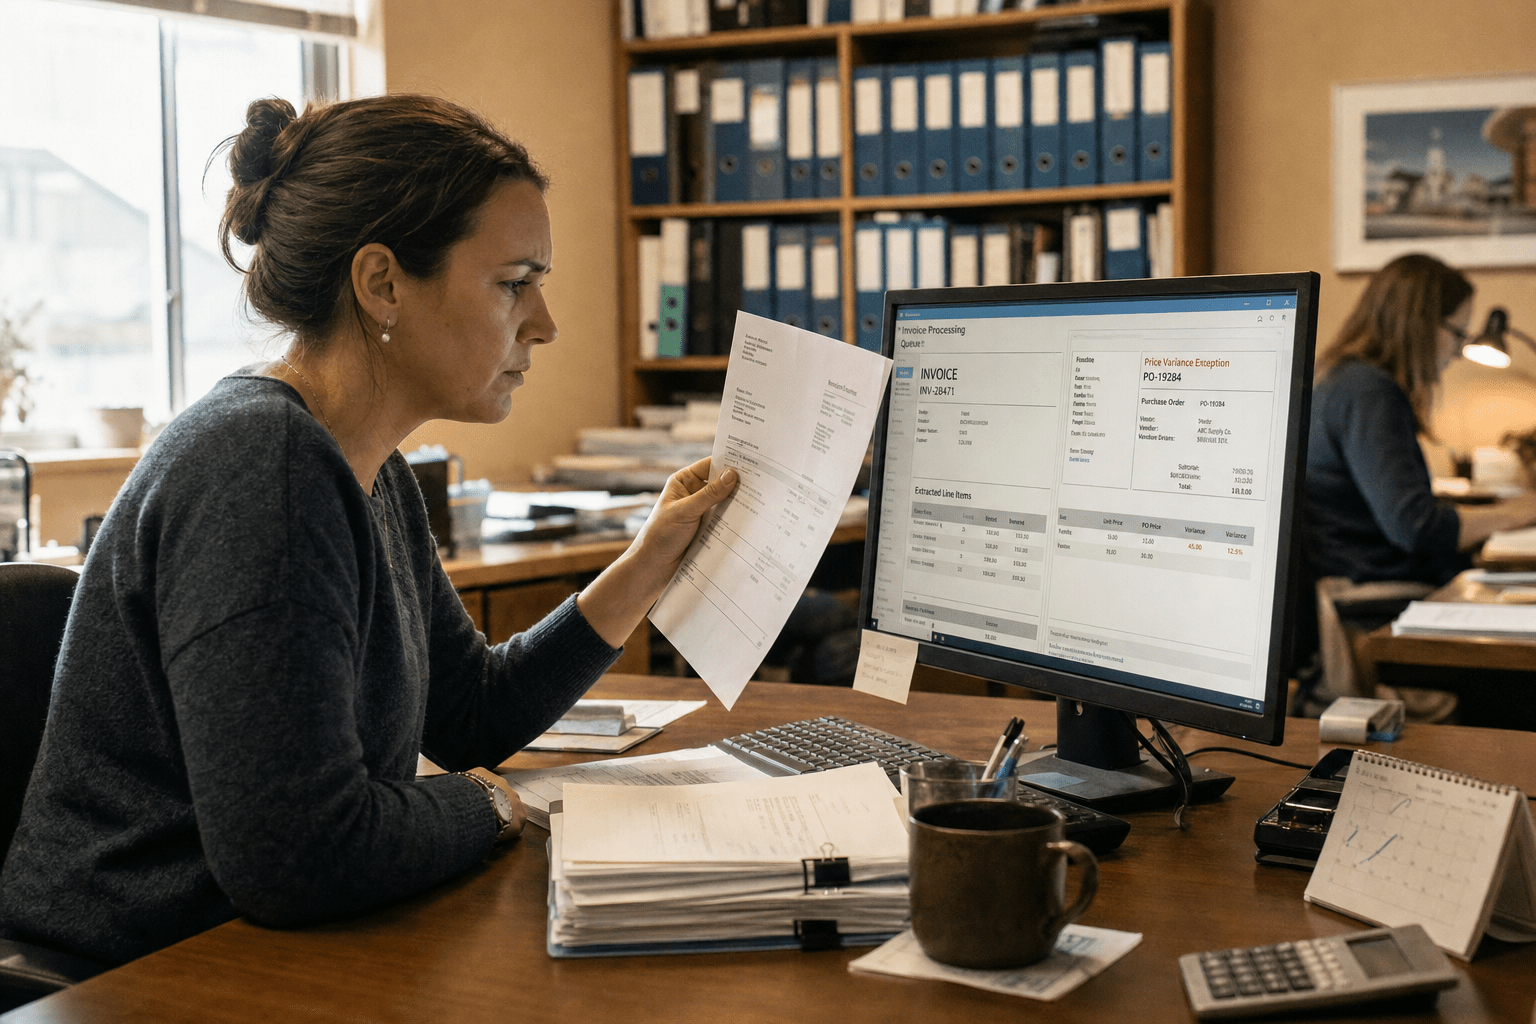
The work is in the exceptions. A price differing by four cents from the purchase order. A quantity received short with no credit note. An invoice from a supplier nobody set up properly. A PDF that is a photograph of a printout. A team buried in payables is buried in that queue, and the question worth asking every vendor is which of those specific cases their product resolves without a person, in your environment.
Overview: five things that decide whether AP automation pays off
- Exception handling is the product. Touchless rate measures the invoices that were already easy.
- Your ERP integration depth caps the benefit. A tool that cannot post directly leaves the clerk retyping.
- Supplier master data quality drives your match rate. Duplicate and inconsistent supplier records defeat matching.
- Tolerance thresholds are a finance policy, not a setting. Somebody has to decide what variance is acceptable.
- Automation changes your fraud exposure. Fewer eyes on invoices means the controls must move elsewhere.
Written for finance managers, controllers and operations leaders at 10 to 500 person organisations processing a few hundred to a few thousand invoices a month.
Exception handling is where the value actually is
Exception handling determines whether an automation project reduces workload or relocates it. A tool achieving a high touchless rate while routing every exception to the same manual queue has changed which invoices your clerk touches, not how many hours they spend.
The evaluation question is therefore specific and awkward for vendors: for each of my top exception types, what does your product do. Not whether it flags them, which everything does, but whether it resolves them.
List your exception types before you talk to anyone
Pull three months of invoices and categorise everything that needed a human. Most organisations find five or six recurring types covering the large majority: price variance within tolerance, quantity mismatch, missing purchase order, unrecognised supplier, duplicate submission, and unreadable document quality.
That list is your specification. It takes an afternoon and it changes the conversation from a feature demonstration into a comparison against your actual work, which is the only comparison that predicts anything.
Some exceptions should never be automated
Two categories deserve a permanent human: any invoice from a supplier whose bank details have changed, and any first invoice from a new supplier. Both are the classic payment fraud patterns, and automating them removes the check most likely to catch one.
Keeping them manual costs very little because they are rare. It is also the control an auditor will look for, and it belongs in the same documented control set as the rest of your cybersecurity compliance position.
ERP integration depth caps the benefit
The tool has to write into the system where payments happen. Extraction and validation deliver nothing if the output is a file somebody keys into the accounting system, and a surprising number of deployments end up exactly there.
Integration quality varies sharply by ERP and by product pairing. Established connectors to the major mid-market platforms are usually solid. A less common accounting package, or an older on-premises version, frequently means a file-based interface with all the reconciliation that implies.
Ask what it writes, not what it reads
Request the specific list of what the tool can post: the invoice header, the line items, the general ledger coding, the purchase order match result, the approval trail. Compare that against what your team enters today.
Whatever is missing stays manual after the purchase. Where the ERP question is still open, it is worth settling first, because the integration options differ meaningfully between platforms, as we cover in our comparison of NetSuite and QuickBooks.
Coding is where accuracy claims get vague
General ledger coding is the step vendors describe least precisely. Suggesting a code based on supplier history works well for repeat purchases from consistent suppliers and poorly for anything unusual.
Ask how coding accuracy is measured and on what mix of invoices. A figure produced against repeat suppliers tells you nothing about the one-off purchases that are usually the ones needing thought.
Supplier master data decides your match rate
Three-way matching compares the invoice, the purchase order and the goods receipt. It works when the supplier record is clean and consistent, and it fails quietly when the same supplier exists three times under slightly different names because three people set them up.
Most organisations have this problem and have not measured it. The symptom is a match rate that stays stubbornly below what the vendor promised, and the cause is in your data rather than in the tool.
Deduplicate before you deploy
Run a duplicate check across your supplier master and consolidate. Standardise naming, remove records with no activity in two years, and confirm bank details on the ones that remain.
This is the same class of preparatory work as any data project, and like most of them it delivers value independently: a clean supplier master reduces duplicate payments whether or not you automate anything. The broader pattern is covered in our piece on costly workflow automation mistakes, where unclean inputs are the recurring theme.
Goods receipt discipline matters as much
Three-way matching also depends on somebody recording receipt. In organisations where goods arrive and the receipt is entered days later or in batches, matching fails on timing rather than on content.
That is a warehouse process question rather than a finance one, and it needs resolving before matching automation can work. Automating on top of an unreliable receipt process produces exceptions the tool cannot fix and the finance team cannot explain.
Tolerance thresholds are a finance decision
Every matching system needs tolerance rules: how much price variance is acceptable, how much quantity variance, and whether tolerance is a percentage or an absolute amount. Vendors ship defaults and the defaults are guesses about your business.
Setting these is a finance policy decision with a real trade-off. Tight tolerances catch more errors and generate more exceptions. Loose ones process smoothly and let small overcharges through, which across thousands of invoices is not a small number.
Derive them from your own variance history
Look at the price variances that actually occurred over a year and where the genuine errors sat within that distribution. That tells you where to set the line far better than a round percentage.
Revisit annually, and separately by supplier category where the pattern differs. A tolerance appropriate for commodity supplies is usually wrong for specialist services.
Automation changes your fraud exposure
Fewer human eyes on invoices is the point of the project and it is also a control change. The traditional protection was a clerk who noticed that a familiar supplier’s bank details looked different this month. Remove that and the control has to exist somewhere else.
Three replacements do most of the work: bank detail changes always route to a human with an independent callback, new suppliers are verified out of band before their first payment, and someone reviews the automation’s approvals periodically rather than trusting them indefinitely.
Duplicate detection is a genuine gain
Automation is better than people at one important thing here: spotting the same invoice submitted twice with a slightly different reference. That is a common source of loss and it is exactly the pattern a system catches and a busy person does not.
So the fraud picture is not uniformly worse. It moves, and the exposures that grow need controls designed deliberately rather than inherited. This balance between what automation improves and what it removes is the theme of our piece on AI agents versus traditional automation.
What a realistic rollout looks like
Start with one supplier category, ideally high volume and low complexity, and run it alongside the existing process for a month. Compare what the tool produced against what your team produced, invoice by invoice, and look specifically at how it handled the exceptions.
Widen category by category. The organisations that deployed across everything at once are the ones we most often hear describe the project as having created work, because every unhandled exception type arrived at the same time and the team lost confidence before the tuning was done. Our overview of AI agents for finance covers the wider set of processes worth sequencing this way, and where the platform needs ongoing operational ownership it sits alongside managed IT services rather than being left to finance alone. The general case for this staged approach is set out in our piece on automation in managed IT services, and the deployment work itself is what we handle under AI agents.
Frequently Asked Questions
What touchless rate should we expect?
Ask instead what happens to your specific exception types, because touchless rate describes the invoices that were already straightforward. A high figure alongside an unchanged exception queue means the work moved rather than reduced, and the exception queue is what your team actually feels.
Do we need purchase orders for this to work?
Three-way matching needs them, and non-purchase-order invoices can still be automated through coding suggestion and approval routing rather than matching. Many organisations run both paths. If most spend has no purchase order, expect a smaller benefit and set expectations accordingly.
How long does implementation take?
Plan on a quarter for a first category, most of which is supplier data clean-up, tolerance decisions and integration testing rather than software configuration. Rolling out across everything at once is the common error and it usually costs more time than it saves.
Will this replace our accounts payable clerk?
Usually it changes the role rather than removing it. The keying disappears and the exception judgement, supplier relationships and controls work remains, which is the part that needed a person all along. At higher volumes it typically avoids the next hire rather than removing the current one.
What is the biggest risk?
Removing the human who would have noticed a supplier’s bank details changing. Automation improves duplicate detection and weakens that check, so bank detail changes and first invoices from new suppliers should always route to a person with an independent callback.
Who is behind this guidance
Our team works across the ERP, finance and integration layers that mid-sized organisations run, which is where the distance between an extraction accuracy figure and a working accounts payable process shows up. We have run the three-month exception analysis that found six recurring types nobody had ever counted, and we have also cleaned a supplier master where one vendor appeared four times and quietly explained a match rate everyone had blamed on the software. Both are why this article starts with exceptions and data rather than with products.
Matt Rosenthal, our CEO, asks the same question of every automation proposal: which control are we removing, and where does it go instead. In accounts payable that question has a specific and well-known answer, which is why bank detail verification appears here as a permanent human step rather than a phase-two consideration.
Count your exceptions before you compare products
The finance teams getting real value from invoice automation in 2026 started by counting what actually goes wrong. They categorised three months of exceptions, cleaned the supplier master, set tolerances from their own variance history, decided which cases would always stay human, and only then asked vendors how their product handled that specific list. The comparison was short and the answer was clear.
If you are evaluating now, the most useful afternoon you can spend is not in a demonstration. It is categorising the invoices your team had to touch last quarter, because that list is the real specification.
Book a free strategy call and we will work through your exception profile and integration options with you.